


Where Americans Prefer To Buy Groceries.
By Errol Schweizer and dunnhumby, with market data courtesy of Chain Store Guide.
H-E-B, Market Basket and Woodman’s are the top three U.S. grocery retailers according to dunnhumby’s ninth annual Retailer Preference Index (RPI) for U.S. Grocery, a comprehensive, nationwide study that examines the approximately $1 trillion U.S. grocery market.
The Texas-based regional grocer has ranked first for the fifth time in nine years. Market Basket ranked second for the second time, while Wisconsin-based Woodman’s, appearing in the RPI for the first time, replaced Costco as the third top U.S. grocer. Woodman’s was also chosen as The Checkout Grocery Update’s 2025 Grocer of the Year. For the first time, the leading three retailers in the United States are all regional chains.
Costco (4), Aldi (5), Winco Foods (6), Trader Joes (7), Amazon (8), Wegman’s (9), and ShopRite (10) round out the 10 highest ranked grocers.
»The RPI found that 41% of a retailer’s long-term success is based on “saving customers money” through competitive pricing, promotions, and rewards — up three points from last year and marking a new record high. This remains the most important of the five customer perception pillars. Retailers who excel at delivering savings consistently achieve stronger, long-term market success in the United States.
U.S. consumers prioritize “saving money” on groceries more than their peers in other developed countries, according to a global dunnhumby RPI analysis, due to higher insecurity rates of basic human needs (Global Social Progress Imperative Study). Grocery prices have increased by over 35% since 2019, and many of the top selling categories have increased 50% or higher.
»According to dunnhumby’s Consumer Trends Tracker, 56% of Americans cannot cover a $400 emergency, a metric that has worsened since December 2024. Meanwhile, 58 million Americans—more than the entire population of Canada—experience food insecurity and occasionally skip meals due to affordability issues.
Quality and value are converging in retail. Savings-focused retailers like Walmart and Aldi are driving this shift, narrowing quality perception gaps with traditional competitors while expanding their price advantage. As a result, quality has emerged as a key competitive differentiator alongside affordability.
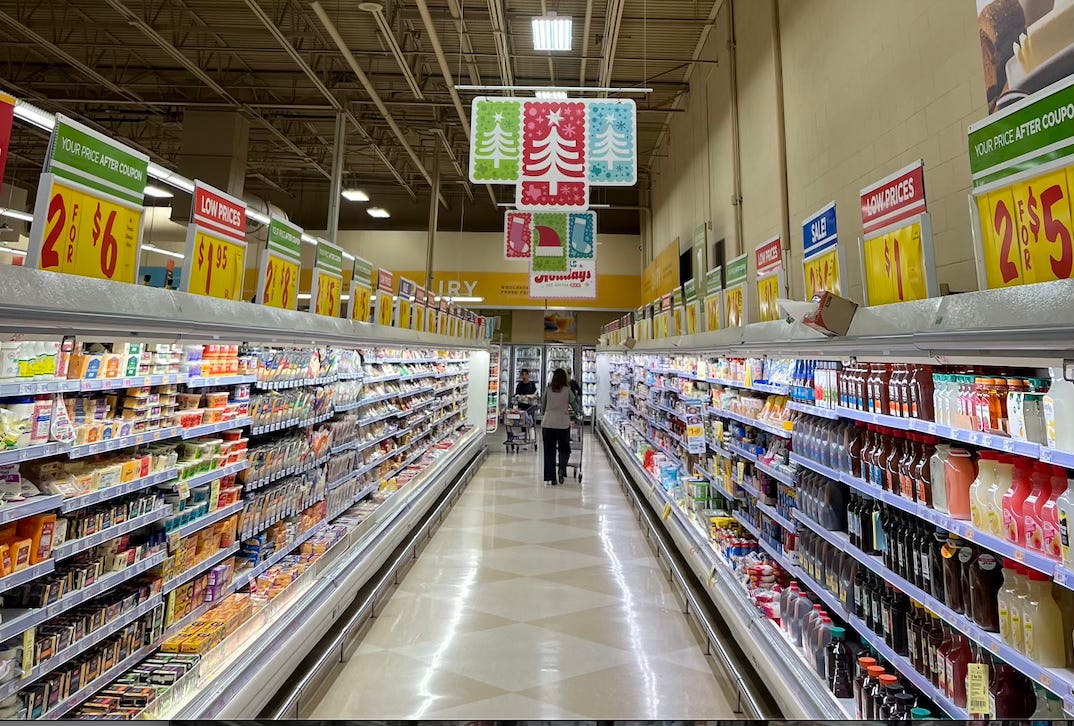
For now, H-E-B remains firmly entrenched as the top retailer due to its superior ability to deliver a combination of better savings, quality, experience, and assortment. HEB dominates much of Texas, with over $28 billion in sales across almost 435 stores, averaging over $80 million a year per store. HEB has an average of over 40% market share everywhere it operates, including over 50% share in some of its largest markets, including San Antonio and Austin, while maintaining a 25% share in Houston that puts it ahead Kroger and Walmart. HEB is also the only regional grocer that dominates Walmart. HEB is loved by customers for a wide variety of reasons, primarily low prices, a broad assortment, new product innovation, strong private labels, a full service shopping experience and a great place to work.
Market Basket is a Boston-area employee owned icon renowned for low prices and great service. The company, which continues to deal with executive infighting, has over 80 locations and does over $6.5 billion in annual sales, around $76 million a year per store. The chain averages 18% market share and is a leader in Boston with 54 locations and 22% share, and Manchester and other areas of southern New Hampshire. Market Basket is attracting a young cohort of customers wary of high prices and algorithmic price manipulation, who are clueing in to why their grandparents are so loyal to the chain. Market Basket is loved by customers for low prices, great private labels, consistent pricing, great service and a full assortment for everyone.
Woodman’s captured third place in the rankings in its first year in the RPI. The retailer was able to leapfrog the competition through strong results in the top two most important pillars - price, promotions, and rewards (pillar 1) and quality (pillar 2) as well as finishing second overall in operations (pillar 4). Woodman’s is an employee-owned regional grocer, with $1.8 billion in annual sales, and 19 locations across Wisconsin and northern Illinois. Their stores can be up to 200,000 square feet and do close to $90 million a year each. Woodman’s is loved for good service and stock levels, low prices and great promos, and a wide variety of products for all needs, including several aisles of natural/organic products and massive frozen, dairy and international food aisles.
Amazon, the leading U.S. grocer in 2021 and 2022, dropped two spots, while Sam’s Club fell six places. Their rankings declined mainly because the digital pillar became less important in 2025, which had been a key strength for both retailers. In addition, neither Amazon nor Sam’s Club ranks in the first quartile for price, promotions, rewards (pillar 1), or quality (pillar 2). Amazon’s Whole Foods banner does just over $20 billion a year and rarely does more than low single digit market share in its service areas. The chain’s growth has slowed since the acquisition, but still maintains leadership in organic and “better for you” merchandising, quality standards and supplier development, despite being an expensive customer for many brands. Amazon’s eponymous stores have suffered from poor sales and customer perception and the company is continuing to reposition their brick and mortars to better compete with Aldi, Walmart and Kroger. Amazon is ranked #1 for digital and fares well in new items, product variety, healthy options, and easy checkout.
Costco is the leading membership-based, wholesale club chain, boasting sales of over $150 million per location, with nearly 900 locations so far. Costco is neck and neck with Kroger for second largest grocery chain, and continues to gain market share. Costco averages around 14% market share where it operates and rarely owns more than 15%. Costco’s largest markets include major metro areas such as NYC, LA, Chicago, Houston, Dallas, Phoenix, DC, Seattle and SF, giving it a very different strategy than larger rival Walmart/Sam’s Club, which focuses on rural areas and heartland suburbs and small cities. Costco also takes a maximum product markup in stores of 14% in order to keep prices down, and half of its net income comes from membership fees. Costco’s formula of large sizes/package formats, low markups, large volume buys at lowest everyday cost, private labeling (Kirkland is the second largest private label brand after Great Value) and rotational/seasonal/limited time offers, have enabled it to sell comparable products at 40 cents on the dollar compared to traditional grocers, making it a consistent destination for committed shoppers willing to buy in volume. Costco is ranked #1 for operations, bulk sizes and private label savings.
Aldi is a massive discount chain, based in Germany, with over 2400 locations, and hundreds more in the pipeline. Aldi boasts prices that undersell Walmart and dollar stores, runs low-margin operations through a strategy of everyday low cost pricing, slim labor scheduling in stores, centralized supply chains and an emphasis on private labels. Aldi does $15 billion in sales per year and rarely registers more than a 3% market share, even when it has dozens of stores in a metro area like Atlanta, Chicago or Dallas. Stores typically generate around $6-7 million per year, relatively low compared to competitors, but this is how Aldi can practically open stores in the parking lots of Stop & Shop or Walmart and run a profitable operation. Aldi is also one of the fastest growing chains, as more customers are prioritizing saving money over loyalty or service. Aldi is ranked #1 for low prices.
Winco Foods is an employee-owned chain across the western U.S. with 139 stores. Winco stores generate on average $65 million a year and typically hold single digit market share, occasionally creeping up into the low teens in some areas with multiple stores. Winco’s largest markets include Portland, Dallas, Riverside, Boise, Seattle and Phoenix and usually has just 1-2 stores per metro area. Winco is ranked among the highest for pricing and promotions value.
Trader Joe’s is a 579 store chain with over $17 billion in annual sales, an average of over $30 million a year each. Trader Joe’s largest markets are LA, SF, NYC, Chicago, Seattle and Washington DC. While the chain boasts a dedicated cult following of overeducated, underpaid enthusiasts, it mostly sells kitchy, creative natural and specialty foods at a discount price. Trader Joe’s follows a similar business model as Aldi or Lidl: centralized distribution and supply chains, flexible, non-union labor in stores, everyday low pricing (no markdowns) and an emphasis on private label. Trader Joe’s rarely registers more than low single digit market share in service areas and instead focuses on dedicated, niche customers while competing head to head with Whole Foods, Sprouts and other discounters. Trader Joe’s is seen as a leader in pricing, variety, private label and overall quality (despite high profile recalls).
Wegman’s is a family-owned, 111 store chain on the east coast that consistently ranks high among being the best places to work. The stores are massive sized and do massive volumes, typically over $115 million a year. Wegman’s rarely maintains dominant market share and instead typically boasts high single digit to low double digit share, averaging around 15%. Wegman’s top markets for both sales and market share include headquarters of Rochester, NY, where it holds nearly 50% share, as well as Buffalo, NY, with a 30% share, and Washington DC and Philadelphia. Wegman’s is a leader in quality, natural/organic products, variety and assortment breadth, clean stores and healthier options.
ShopRite has over 210 locations and $12.3 billion in sales across several ownership groups in the Northeast and Mid-Atlantic states. Locations generate around $58 million a year. ShopRite is a market share leader in a few smaller markets in southern and central New Jersey as well as upstate NY but is in general a well-regarded operator throughout the NYC and Philadelphia metro areas. ShopRite is also a member of Wakefern, a $22 billion retail-owned wholesale cooperative based in New Jersey. ShopRite ranks high for promotions, couponing and discounting, as well as a wide variety and a one stop shopping experience.
And lastly, The Defense Commissary Agency, America’s leading public sector grocery, boasts 178 locations across the country on military bases. Locations do an average of $28 million a year each, and DeCA typically holds 5-6% market share in the areas it operates, competing with Walmart, discounters and other supermarket chains. DeCA stores sell groceries at a cost plus 3-5% over wholesale, leverage scale to keep costs down, utilize private sector supply chains, sales brokers, and wholesalers like Spartan Nash, and operate through public subsidies that cover labor, utilities, shrink and other retail overhead. DeCA saves service members nearly $2 billion a year in retail markups, and if it were a traditional grocer, it would generate over $7 billion a year, nearly as large as Sprouts Farmers Markets. DeCA stores are well regarded for low prices, bulk buys, carrying a wide variety and offering customers a full service shopping experience. DeCA is ranked #27 on the dunnhumby retailer preference index for 2025, just ahead of Smith’s and Schnuck’s, and just behind Hannaford and Big Y.
Erich Kahner, dunnhumby’s Americas Sr. Director, Strategy & Insights sums it up, “I think three important things that stick with me after writing this year’s report is: the importance of affordability in not just driving results for retailers but in ensuring a life of dignity for many financially insecure Americans; regional supermarkets are not dead and can in fact thrive against national non-conventionals; how as the industry evolves superior execution of the retail basics in grocery are still paramount to winning.”
Thanks for this - we have started tracking grocery prices in the DMV and found huge differences in prices, sometimes several dollars, for the exact same product across grocery and retail stores - unfortunately no HEB's in this region!
Great post. Would love to understand how produce sourcing and pricing strategies fit into the consumer preference equation.